What Mistakes Can Complicate a Florida Insurance Bad-Faith Claim?
A denied insurance claim can leave you facing repair bills, medical expenses, or a lawsuit with no clear way forward. The mistakes that complicate a Florida insurance bad-faith matter often happen during the claim itself: waiting to report a loss, losing evidence, ignoring information requests, filing an imprecise notice, or signing a settlement without understanding what it resolves.
A coverage disagreement and a bad-faith claim raise different questions. Your policy determines what the insurer agreed to cover; the claim history helps show whether it handled its obligations fairly. Property and liability claims also follow different procedures. Start by identifying the policy, what the insurer did, and how that conduct affected you.
The steps below explain common problems in Florida insurance disputes and how to keep the information needed for a legal review. The rules that apply can depend on your policy and claim dates, particularly for older policies and pending cases.
Have Questions About An Insurance Bad-Faith Claim?
Call us or request a case review by our experts.
1. Treating every denial or low offer as proof of bad faith
An insurer may dispute whether a policy covers a loss, how much damage occurred, or whether another exclusion applies. Those disputes require attention, but calling them bad faith does not answer the underlying coverage questions. Section 624.155 addresses specified misconduct, including failing to attempt a settlement when the circumstances called for fair and honest treatment of the insured. It also expressly states that mere negligence alone is insufficient.
Start with the insurer’s stated reason. Compare that reason with the complete policy and the evidence actually supplied. For example, if a denial says a loss occurred outside the policy period, the date-of-loss evidence matters. If an estimate omits a damaged room, photographs and an itemized competing estimate may clarify the disagreement. A documented explanation of what the insurer overlooked is more useful than an accusation unsupported by the file.
Florida’s unfair-claims statute identifies conduct such as unreasonable investigations and failures to explain denials. A lawyer must still connect the specific facts, applicable provision, procedural requirements, and damages; an administrative violation does not establish every element of a civil claim.
Sources: Florida Statutes § 624.155 — Civil remedy; Florida Statutes § 626.9541 — Unfair methods of competition and unfair or deceptive acts or practices defined.
2. Confusing claim-reporting deadlines with lawsuit deadlines
Reporting a loss and filing a lawsuit are different steps. Under the current general property-claim rule in section 627.70132, notice of a claim or reopened claim must be given within one year after the date of loss; a supplemental claim has an eighteen-month notice period. These are outside limits, not permission to disregard a policy’s prompt-notice requirements. The statute contains special provisions, including for qualifying military deployment and condominium loss assessments.
A reopened claim seeks additional costs for damage previously disclosed after the insurer closed the claim. A supplemental claim concerns additional loss or damage from the same peril after adjustment, or additional costs incurred during repairs under a timely reported open claim. Choosing the wrong label can obscure the applicable deadline. Keep the original notice, closure letter, repair records, and dates of each additional submission.
Section 95.11 separately governs lawsuit limitations. Do not assume the claim number remains open indefinitely or that ongoing telephone negotiations preserve the right to sue. Obtain a deadline review using the actual loss date, policy dates, claim type, and procedural history. A single deadline quoted for all Florida insurance disputes can be misleading.
Sources: Florida Statutes § 627.70132 — Notice of property insurance claim; Florida Statutes § 95.11 — Limitations other than for the recovery of real property.
3. Keeping an incomplete record of what the insurer received
A claim file needs more than the final denial. Preserve the declarations page, policy forms and endorsements, correspondence, estimates, photographs, bills, proof-of-loss submissions, and any payment documents. Save email attachments and upload confirmations. A document sitting on your computer does not show that the insurer received it.
Prepare a simple chronology: when the loss occurred, when notice was provided, what information was requested, when you responded, and what happened next. Florida DFS recommends detailed communication records and supporting documentation. For property claims, section 627.70131 also requires insurers to maintain specified dated claim records. Your own chronology helps identify what to request and where the parties’ accounts differ.
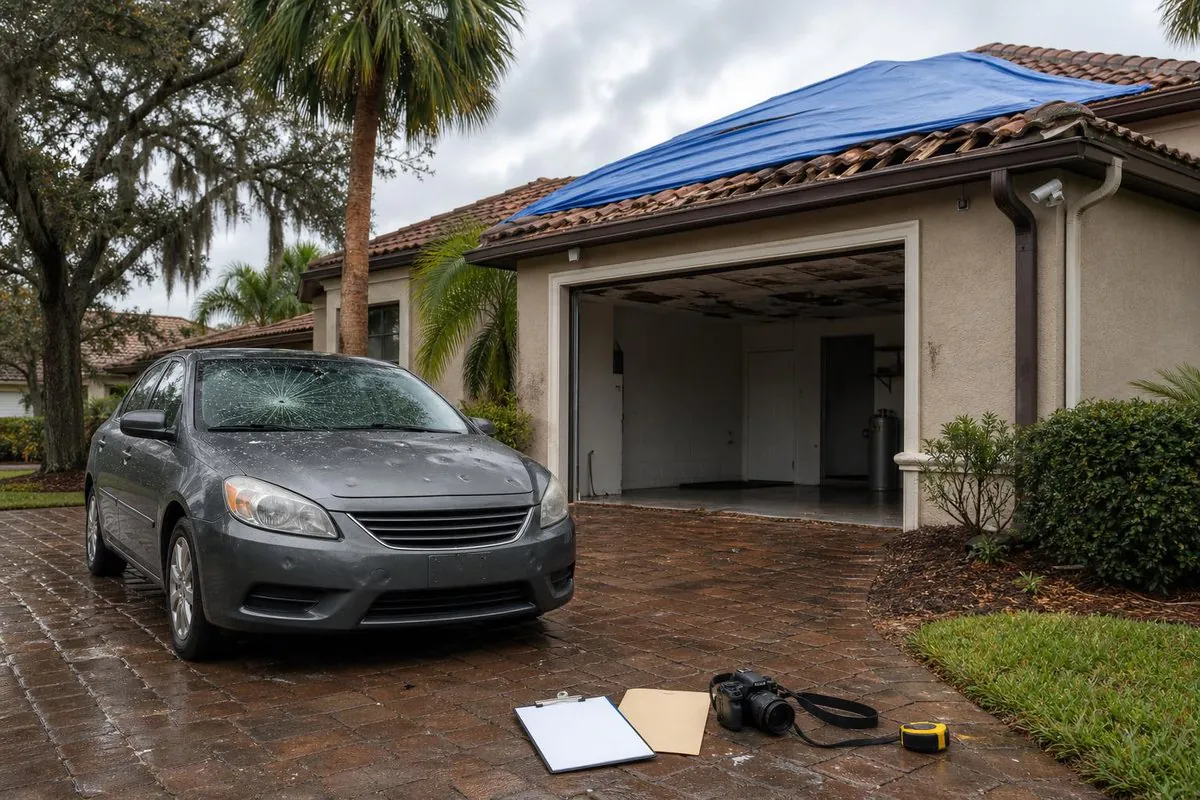
Document conditions before repairs when safely possible, while taking reasonable steps to protect people and prevent further damage. Preserve estimates and invoices showing why emergency work was needed. Distinguish firsthand observations from assumptions: “water entered the bedroom on this date” is different from asserting a cause that no qualified inspection has established. These are evidence-preservation practices, not a reason to delay necessary safety measures.
Sources: Florida DFS — Get Insurance Help; Florida Statutes § 627.70131 — Insurer’s duty to acknowledge communications regarding claims; investigation.
4. Ignoring information requests or filling gaps with guesses
Repeated information requests can be frustrating, especially when you believe the insurer already has what it needs. Keep a copy of each request, check what you have supplied, and ask for clarification when necessary. If a document is unavailable, explain the difficulty in writing so the claim file shows what you did to respond.
Section 626.9541 addresses an insurer’s failure to identify needed information or explain why it is necessary. Conversely, section 627.70131 recognizes certain policyholder conduct, including lack of cooperation that reasonably prevents compliance, as a factor beyond an insurer’s control. The lesson is to create a clear record of cooperation and of any disputed request rather than simply going silent.
Do not inflate estimates, invent expenses, or state uncertain facts as established. Correct an inaccurate submission promptly and retain both versions. If the insurer requests a sworn statement, examination, or broad authorization that you do not understand, have the policy and request reviewed before deciding how to respond. Cooperation should be accurate and informed.
Sources: Florida Statutes § 626.9541 — Unfair methods of competition and unfair or deceptive acts or practices defined; Florida Statutes § 627.70131 — Insurer’s duty to acknowledge communications regarding claims; investigation.
5. Using a consumer complaint as a substitute for a Civil Remedy Notice
An ordinary complaint to Florida DFS can seek consumer assistance, but it is not interchangeable with the statutory Civil Remedy Notice. Section 624.155 requires sixty days’ written notice to DFS and the authorized insurer as a condition of a statutory action. DFS uses a dedicated filing system and transmits the notice to the insurer’s designated contact.
Specificity matters. The notice must identify the statutory language allegedly violated, the facts and circumstances, involved individuals, relevant policy language where required, and its purpose of perfecting the statutory remedy. Copying a long list of provisions into a generic complaint may leave the actual alleged violation unclear. The statute contains a policy-language exception for a third-party claimant who requested but was not provided the policy.
Verify the underwriting company’s correct legal identity before filing. DFS explains that submitted notices cannot simply be edited afterward. Its system also makes notices public, so avoid unnecessary sensitive information. Save the filed notice and confirmation, and have the receipt date and cure-period calculation checked. A submitted form is not a court determination that the notice is legally sufficient.
Sources: Florida Statutes § 624.155 — Civil remedy; Florida DFS — Civil Remedy and Required Legal Notices; Florida DFS — Civil Remedy Frequently Asked Questions.
6. Suing too early or misunderstanding appraisal
In property-insurer claims for extracontractual damages under section 624.155(1)(b), section 624.1551 requires an adverse court adjudication of breach of the insurance contract and a final judgment or decree against the insurer. Payment of an appraisal award, or acceptance of an offer of judgment under section 768.79, does not satisfy that statutory prerequisite. A difference between the insurer’s appraisal estimate and the award may be evidence, but does not alone create the cause of action.
Appraisal also affects notice timing. Section 624.155 prohibits filing its notice within sixty days after any party invokes appraisal in a residential property claim. The statutory cure period is another separate issue: if the insurer pays the damages or corrects the circumstances within sixty days after receiving the department’s notice, the statute says no action lies. Finishing one step does not mean every prerequisite is satisfied.
Before filing suit, have counsel map the underlying contract dispute, any appraisal, the notice process, and the proposed bad-faith theory. That sequence helps avoid spending time on a lawsuit whose required foundation has not yet been established.
Sources: Florida Statutes § 624.1551 — Civil remedy actions against property insurers; Florida Statutes § 624.155 — Civil remedy.
7. Making an unsupported demand or using an artificial deadline
Liability claims require their own analysis. Section 624.155(4) provides a protection against liability bad-faith actions, including common-law actions, when the insurer tenders the lesser of the policy limits or the amount demanded within ninety days after receiving actual notice accompanied by sufficient supporting evidence. A demand letter without the material needed to assess its amount may create a dispute about when that statutory period began.
The same statute requires insureds, claimants, and their representatives to act in good faith when furnishing information, making demands, setting deadlines, and attempting settlement. A factfinder may reduce a bad-faith damages award for a failure to meet that duty. Deliberately obstructing evaluation or setting a deadline designed to be impossible can complicate the case instead of strengthening it.
A sound demand explains the requested amount, includes available supporting records, identifies the proposed settlement terms, and preserves delivery evidence. If several injured people are pursuing limited coverage from one event, ask how competing claims affect the process. Section 624.155 contains additional protections involving timely interpleader or agreed binding arbitration; the first demand does not necessarily exhaust that analysis.
Sources: Florida Statutes § 624.155 — Civil remedy.
8. Accepting payment without reviewing the terms or assuming extra damages are automatic
A partial payment and a full settlement can have very different consequences. Section 627.70131 requires explanatory language with property payments that are not full and final. Separately, section 673.3111 can discharge a disputed claim when a qualifying instrument is tendered and collected as full satisfaction, subject to its conditions and exceptions. Read the check, accompanying letter, and any release together before acting.
Bad-faith damages also require proof. Section 624.155 allows reasonably foreseeable damages resulting from a specified violation, potentially exceeding policy limits. Punitive damages have additional requirements involving a general business practice and specified aggravated conduct. Neither a denial nor the expiration of a notice period guarantees a particular recovery. Preserve records of the claimed harm and its connection to the insurer’s conduct.
Sources: Florida Statutes § 627.70131 — Insurer’s duty to acknowledge communications regarding claims; investigation; Florida Statutes § 673.3111 — Accord and satisfaction by use of instrument; Florida Statutes § 624.155 — Civil remedy.
How RDCY can help evaluate an insurance bad-faith dispute
If an insurer’s handling of a claim has put your financial security or injury recovery at risk, you need to understand the policy, the claim history, and the legal options available. Rafferty Domnick Cunningham & Yaffa handles Florida insurance coverage and bad-faith litigation. We examine the underlying claim and settlement communications before drawing conclusions about the insurer’s conduct.
Fred Cunningham focuses on insurance-company bad faith, coverage disputes, and catastrophic injuries, and is Florida Bar board certified in civil trial law. He has also taught fellow attorneys about defense tactics in bad-faith cases at the February 2025 Workhorse Seminar and about resolving excess claims before a bad-faith lawsuit in 2024. That work addresses issues that can matter directly to your claim, including settlement opportunities, policy limits, and the terms of a proposed payment.
Cunningham and Gregory Yaffa obtained a nearly $8 million jury verdict in a Jacksonville bad-faith trial on January 26, 2018. The case involved settlement handling and a hospital lien, showing how payment terms can become central to an insurance dispute. This was a jury verdict, and the outcome of your case will depend on its own facts. Past results do not guarantee a similar outcome.
Sean C. Domnick is certified in civil trial law by The Florida Bar and the National Board of Trial Advocacy. His work includes serious medical injuries and nursing-home litigation, where evaluating the underlying harm and available coverage can be closely connected. He has taught on missed strokes in 2024, stroke diagnosis and treatment litigation in 2021, nursing-home claims in 2020, and coverage in nursing-home neglect cases in 2017.
Domnick served as American Association for Justice president in 2023–2024 and wrote the Trial President’s Pages “A Collective Effort” in December 2023 and “Treating Workers Fairly” in January 2024. He received the 2023 Joe Tonahill Award and the 2024 Best Lawyers “Lawyer of the Year” recognition for plaintiffs’ medical-malpractice law in West Palm Beach. Alongside Cunningham’s insurance practice, his serious-injury litigation experience contributes to a team that can examine the claim, the insurer’s response, and the consequences for the person seeking coverage.
Bring the policy, correspondence, claim timeline, notices, and any proposed release. We can review the insurer’s reasons, identify missing evidence, and explain which steps need attention before a bad-faith claim can proceed. Understanding that sequence can help you protect your rights while deciding how to respond to a denial or settlement proposal.
Learn more about our attorneys, professional background, and relevant work: AAJ — Sean Domnick: President, 2023–2024; AAJ — Sean Domnick Sworn in as New President of Plaintiff Trial Bar; AAJ Trial — Treating Workers Fairly.
Related resources
Need Help Understanding An Insurance Bad-Faith Claim?
Call us or request a case review by our experts.
Professional Recognition


Recognition applies to the named attorneys and selection years. See the linked profiles for details.
Related RDCY Videos and Social Posts
- RDCY official YouTube channel — official account.
- RDCY official Instagram profile — official account.
- RDCY official Facebook profile — official account.
- RDCY official LinkedIn profile — official account.
Florida Insurance Bad-Faith FAQs
These answers provide general information about Florida insurance claims and bad-faith litigation. Policy terms, claim dates, and the applicable law can change the analysis; an individual file requires legal review.
Does an insurer’s failure to return a call prove bad faith?
No. An unanswered call can be relevant evidence, but it does not by itself establish a Florida bad-faith claim. Section 624.155 states that mere negligence alone is insufficient. Section 626.9541 identifies failures to acknowledge and act promptly on claim communications among unfair claim-settlement practices, but a civil claim requires analysis of the applicable provision and the full facts.
Keep the call date, number, message, and any written follow-up. Your lawyer can compare them with the insurer’s responses and the information it had at the time. That record can help distinguish an isolated missed call from a pattern that delayed a claim decision or prevented a settlement opportunity from being addressed.
Sources: Florida Statutes § 624.155 — Civil remedy; Florida Statutes § 626.9541 — Unfair methods of competition and unfair or deceptive acts or practices defined.
Does the sixty-day property payment rule cover every insurance policy?
No. The sixty-day pay-or-deny rule in section 627.70131(7) applies to the property claims defined there, not every kind of insurance. Its scope includes residential coverage and specified commercial structural, contents, or tenant coverage involving premises or structures of 10,000 square feet or less. The provision also recognizes qualifying factors beyond the insurer’s control.
Determine the policy type before using that deadline to evaluate a delay. The statute requires a reasonable written explanation for a payment, denial, or partial denial, and states that failure to comply with the subsection is not the sole basis for a private cause of action. A delay may warrant investigation, but the applicable duties and additional elements still have to be established.
Sources: Florida Statutes § 627.70131 — Insurer’s duty to acknowledge communications regarding claims; investigation; Florida Statutes § 624.155 — Civil remedy.
Can I wait for all repair estimates before reporting property damage?
Waiting can put a property claim at risk. Section 627.70132 generally bars a claim or reopened claim unless notice is given within one year of the loss, and generally bars a supplemental claim unless notice is given within eighteen months. Notice must also comply with the policy; these statutory periods do not eliminate a prompt-notice provision.
Report the available facts accurately and preserve the initial submission while gathering additional estimates. The statute defines reopened and supplemental claims separately and includes special rules, so later discoveries need their own deadline review. Claim-reporting periods also differ from the time allowed to bring a lawsuit under section 95.11. A pending estimate or an open conversation with an adjuster should not be assumed to extend either deadline.
Sources: Florida Statutes § 627.70132 — Notice of property insurance claim; Florida Statutes § 95.11 — Limitations other than for the recovery of real property.
Will a Florida DFS consumer complaint preserve my statutory bad-faith claim?
A consumer complaint should not be treated as a substitute for the statutory Civil Remedy Notice. Florida DFS offers consumer assistance and separately operates the notice system for section 624.155. That statute requires the department and the authorized insurer to receive the prescribed sixty days’ written notice before a statutory action can proceed.
A consumer-assistance record may help document the dispute, but it does not establish that the legal notice requirements were met. Preserve your complaint and the insurer’s response, then determine whether a separate notice and other prerequisites apply. DFS also states that it does not participate in the presuit negotiations associated with Civil Remedy Notices. Filing in its system does not mean the department has adjudicated liability or approved a lawsuit.
Sources: Florida Statutes § 624.155 — Civil remedy; Florida DFS — Civil Remedy and Required Legal Notices; Florida DFS — Get Insurance Help.
What if my Civil Remedy Notice names the wrong insurance company?
Naming the wrong company can create a notice problem that requires prompt legal review. The statutory process concerns the authorized insurer responsible for the alleged violation, and Florida DFS explains that a submitted Civil Remedy filing cannot simply be changed afterward. The marketing brand, broker, and underwriting company may be different entities.
Check the policy declarations and correspondence to identify the responsible legal entity before filing. If a mistake has already occurred, preserve the original filing and confirmation and obtain advice about the appropriate corrective step and timing. Adding a comment should not be assumed to cure every defect or start the proper cure period. A notice must satisfy the statutory requirements, not just receive an electronic filing number.
Sources: Florida Statutes § 624.155 — Civil remedy; Florida DFS — Civil Remedy Frequently Asked Questions.
Does winning a property appraisal let me immediately sue for bad faith?
No. Under section 624.1551, payment of an appraisal award does not constitute the adverse adjudication required for the property-insurer extracontractual claim addressed by that statute. The law requires a court adjudication that the insurer breached the contract and a final judgment or decree against it. An appraisal difference alone does not create that cause of action.
Appraisal can also affect the timing of a Civil Remedy Notice. Section 624.155 prevents filing that notice within sixty days after appraisal is invoked by any party in a residential property claim. Preserve the invocation, award, payment, and court documents so counsel can review the sequence. A favorable appraisal result and a legally mature bad-faith action are separate questions.
Sources: Florida Statutes § 624.1551 — Civil remedy actions against property insurers; Florida Statutes § 624.155 — Civil remedy.
Must a third-party claimant quote policy language they have not received?
Not always. Section 624.155’s notice requirements contain an exception for a third-party claimant when the insurer has not provided a copy of the policy pursuant to a written request. That exception concerns the reference to specific policy language; it does not eliminate the other required notice information.
Preserve the written policy request, proof of delivery, and the response or lack of response. The notice still needs specific facts, the allegedly violated statutory language, involved individuals, and the required statement of purpose. DFS’s filing instructions explain the submission process, but using its form does not resolve whether the exception fits your circumstances. Review the record rather than omitting policy language merely because obtaining it was inconvenient.
Sources: Florida Statutes § 624.155 — Civil remedy; Florida DFS — Civil Remedy Frequently Asked Questions.
Can I make an insurer’s liability tender deadline shorter than ninety days?
A shorter demand deadline does not eliminate the statutory protection in section 624.155(4). That provision bars a liability bad-faith action, including a common-law action, when the insurer makes the specified tender within ninety days of actual notice accompanied by sufficient supporting evidence. Its trigger depends on the evidence and notice, not simply the deadline printed in a letter.
The statute also requires good faith when setting deadlines, supplying information, and attempting settlement, and permits a reduction of damages for failures in that duty. Provide a supported demand and preserve transmission records instead of assuming a short deadline creates bad faith. The unfair-claims statute separately addresses reasonable investigation and communications; those duties need evaluation within the complete legal framework.
Sources: Florida Statutes § 624.155 — Civil remedy; Florida Statutes § 626.9541 — Unfair methods of competition and unfair or deceptive acts or practices defined.
Does depositing an insurance check always end the dispute?
No. The effect depends on the payment’s terms and the applicable law. Section 627.70131 expressly addresses property payments that are not full and final. But section 673.3111 provides conditions under which collecting an instrument tendered in full satisfaction of a genuinely disputed or unliquidated claim can discharge that claim, subject to statutory exceptions.
Review both sides of the check, the accompanying letter, and any release before depositing or signing. A routine partial payment differs from an offer expressly resolving a disputed balance or broader claims. Do not assume that crossing out settlement language protects your rights, or that every check prevents further recovery. If you already deposited a disputed payment, retain the documents and obtain timely review of its actual legal effect.
Sources: Florida Statutes § 627.70131 — Insurer’s duty to acknowledge communications regarding claims; investigation; Florida Statutes § 673.3111 — Accord and satisfaction by use of instrument.
Are punitive damages automatic if an insurer fails to cure a notice?
No. Expiration of the cure period does not automatically establish bad faith or entitlement to punitive damages. Section 624.155 imposes additional punitive-damages requirements, including conduct frequent enough to indicate a general business practice and specified malicious or reckless conduct. Compensatory damages also require a supported connection to the violation.
For the property-insurer claim covered by section 624.1551, the adverse court adjudication and final judgment prerequisite still matters. Preserve evidence of the alleged violation and resulting losses, but avoid assigning a guaranteed case value based on a denial or an unanswered notice. Different forms of relief have different elements. A lawyer should evaluate what damages the evidence supports and whether the claim is procedurally ready before requesting a particular award.
Sources: Florida Statutes § 624.155 — Civil remedy; Florida Statutes § 624.1551 — Civil remedy actions against property insurers.
Ready to Discuss Your Insurance/Bad Faith Litigation Matter?
Call us or request a case review by our experts.
NOTABLE RESULTS
Rafferty Domnick Cunningham & Yaffa publishes the following results. This underlying wrongful-death verdict led to the Harvey v. GEICO insurance bad-faith litigation.
$8,470,000 underlying wrongful-death verdict
Read more about these results
- $8,470,000 underlying wrongful-death verdict: Sean Domnick represented the estate; Fred Cunningham pursued the related bad-faith action. The Florida Supreme Court directed reinstatement of the final bad-faith judgment. Read the source account.
Read the firm’s published results
Prior results do not guarantee a similar outcome. Each case is different and must be evaluated on its own facts.